100G Optical Transceivers Market to Reach USD 11,056 Million by 2036 as Network Operators Sustain High-Speed Connectivity

Optical transceivers remain essential components of telecommunications networks, enterprise infrastructure and data-center connectivity. While the industry is progressing toward 400G, 800G and 1.6T technologies, installed 100G networks continue to require replacement modules, capacity upgrades and reliable optical interfaces.
According to SemiconductorInsight, the 100G Optical Transceivers Market was valued at USD 5,292 million in 2026 and is projected to reach USD 11,056 million by 2036, recording a CAGR of 7.6% during 2027–2036. The market covers 100Gb/s optical transmit-and-receive assemblies using lasers, photodiodes, clock recovery, multiplexed lanes and optical-electrical interfaces in multiple MSA form factors. Asia-Pacific represented the largest regional market in 2026, with an estimated share of approximately 42%.
Explore the complete https://semiconductorinsight.com/report/global-100g-optical-transceivers-market/
Why Do 100G Optical Transceivers Remain Important in Modern Networks?
Optical transceivers convert electrical data into modulated light for transmission through fiber and reconstruct electrical signals at the receiving end. They are used in data centers, metro networks and telecommunications infrastructure where reliable high-speed connectivity is required.
100G modules continue to support installed switch ports, server connections and network aggregation equipment. Many operators maintain 100GbE links in existing infrastructure even as new high-performance deployments move toward faster optical standards.
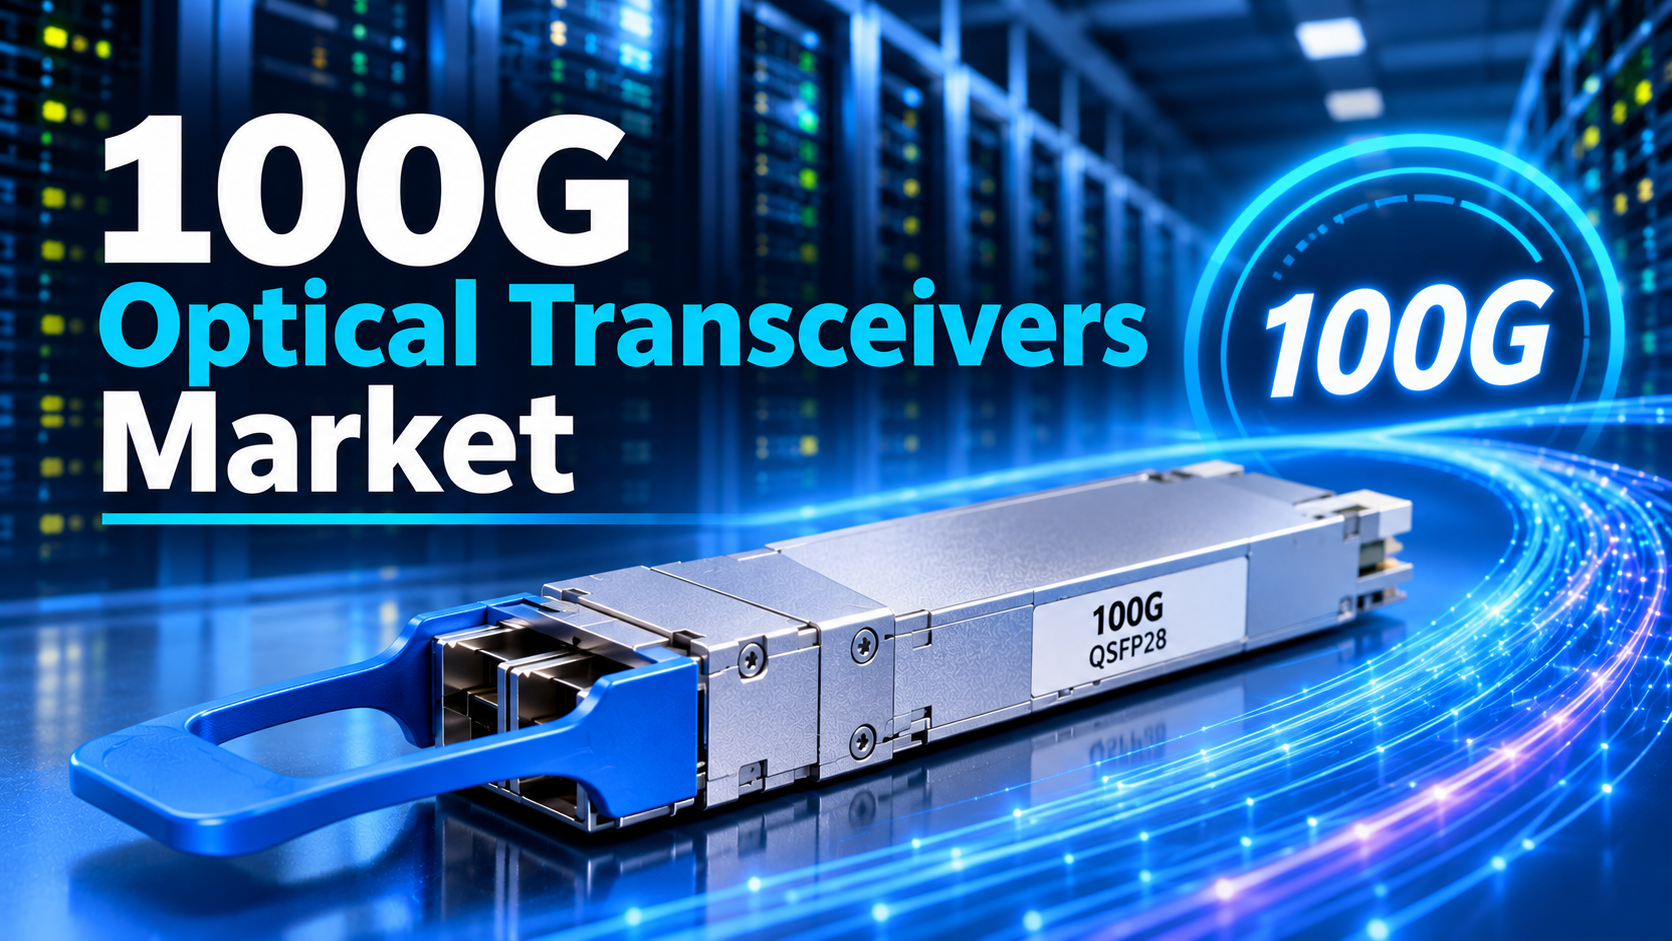
QSFP28 is a widely used physical format for 100GbE, commonly combining four electrical lanes at 25Gb/s. Other form factors remain relevant within the report's classification, although compatibility must be verified at the product and interface level.
The continued use of 100G equipment is therefore closely connected to replacement demand, network maintenance and the economics of upgrading installed infrastructure.
Data-Center and Metro Network Upgrades Support Market Demand
One of the major factors influencing the 100G Optical Transceivers Market is the continued need to maintain and upgrade installed network infrastructure. Operators replace failing transceivers, increase switch-port capacity and expand metro transport networks.
Semiconductor Insight identifies internal data centers as the largest application segment, representing an estimated 46% of 2026 revenue. Existing server and spine-leaf networks continue to support a substantial installed base of 100G QSFP28 links.
Asia-Pacific represents the largest regional revenue pool, with an estimated 42% share in 2026. China has a large optical-module manufacturing and assembly ecosystem, while Japan and South Korea support network refurbishment and high-density cloud links.
Demand is also influenced by the transition toward higher-speed technologies. As customers adopt 400G and 800G for new deployments, 100G purchases increasingly reflect installed-base maintenance and replacement requirements.
Receive your Free Sample Report today: https://semiconductorinsight.com/download-sample-report/
QSFP and Established Pluggable Formats Shape the Technology Landscape
QSFP is the leading type segment in the report, with an estimated 55% revenue share in 2026. QSFP28 remains an important 100GbE interface for installed switch generations because of its density and mature cost position.
The market's type segmentation includes SFF, SFP, QSFP, CFP, XFP and CXP. The report notes that product labels and legacy classifications do not automatically establish 100G compatibility, making qualification at the specific device level important.
Optical transceiver selection depends on receiver sensitivity, signal integrity, thermal behavior, optical reach and host compatibility. These requirements vary across data-center, metro and longer-distance network applications.
As the industry moves toward 400G, 800G and 1.6T, 100G suppliers are increasingly competing on interoperability, replacement availability and lifecycle support.
Internal Data Centers and Metropolitan Networks Create Additional Demand
Internal data centers represent the largest application area for 100G optical transceivers. Existing leaf switches and server connections continue to generate replacement demand where higher-speed ports are not yet economically justified.
Metropolitan-area networks also use 100G optical modules for aggregation and city-to-city interconnects. These deployments depend on optical reach, wavelength planning and compatibility with existing transport equipment.
The report also includes a Remotely application category, covering longer-distance or remote connections where link-budget engineering and transport compatibility are important.
Together, these applications create a market shaped by both established 100GbE installations and the gradual transition to higher-speed optical interfaces.
Interoperability and Lifecycle Support Are Becoming Competitive Priorities
Network operators increasingly evaluate transceivers based on interoperability, optical link budgets and repeat-order availability. A module must work reliably with the host equipment and support the required transmission distance.
Maintenance requirements are important because installed 100G networks can remain in service for years. Buyers need replacement products that preserve compatibility with existing switch ports and network configurations.
Suppliers must also manage pricing pressure as higher-speed modules capture new-build spending. Mature 100G products remain relevant where cost-effective replacement and service continuity are priorities.
These factors make documented performance, qualification evidence and long-term supply support important elements of competition.
Replacement Demand and Affordable Network Capacity Support Market Development
100G optical transceivers can provide a cost-effective option for maintaining installed networks where a full upgrade to higher-speed equipment is not immediately required.
Data-center operators and telecom providers balance the affordability of mature 100G modules against the growing availability of 400G and 800G ports. This creates opportunities for suppliers that can support existing equipment at competitive prices.
Demand is therefore influenced by switch-port replacement cycles, network refurbishment and the availability of qualified modules for specific host platforms.
At the same time, falling average prices and the migration of new infrastructure toward higher speeds can limit pricing power for standalone 100G products.
Access the Full Report for In-Depth Insights: https://semiconductorinsight.com/report/global-100g-optical-transceivers-market/
Higher-Speed Alternatives and Legacy Compatibility Remain Key Challenges
The expansion of 400G and 800G optical ports is a major restraint for the 100G market. New data-center builds increasingly favor higher-rate connections, reducing the role of 100G in new infrastructure.
Legacy pluggable-format incompatibilities can also affect purchasing decisions. Product labels such as SFP or XFP may refer to lower-speed interfaces, so buyers must confirm that a specific module supports the intended 100GbE application.
Price compression is another challenge as mature module supply competes with higher-speed alternatives. Suppliers must maintain product quality and replacement availability while managing commercial pressure.
The report also highlights the importance of qualification, interface reliability and service support throughout the planned operating life of network equipment.
Where Are the Biggest Opportunities Emerging?
Replacement demand in installed data-center networks represents an important opportunity for suppliers of qualified 100G modules. Older switches and lower-tier network domains may continue to use 100G links even as higher-speed equipment is introduced elsewhere.
Metro and regional transport networks also provide opportunities as operators increase backbone capacity and refresh aging optical equipment.
Asia-Pacific offers a significant market because of its large installed network base, optical-module manufacturing ecosystem and ongoing network modernization.
Suppliers able to provide interoperable products, reliable supply and cost-effective lifecycle support may be well positioned to serve customers maintaining 100G infrastructure.
100G Optical Transceivers Market Segmentation
The report evaluates the market across key product and application categories, providing a structured view of demand and deployment requirements.
By type, the market is divided into:
• SFF
• SFP
• QSFP
• CFP
• XFP
• CXP
By application, the market covers:
• Metropolitan Area
• Remotely
• Internal Data Center
This segmentation is relevant for manufacturers and buyers because technical requirements vary by transmission performance, deployment environment, network architecture and end-user application.
View the complete 100G Optical Transceivers Market segmentation and forecast: https://semiconductorinsight.com/report/global-100g-optical-transceivers-market/
Regional 100G Optical Transceivers Market Outlook
Asia-Pacific was the largest regional market in 2026, accounting for an estimated 42% of global revenue, and is also the fastest-growing region in the report. China, Japan, South Korea and India contribute through manufacturing, network refurbishment and expanding connectivity requirements.
North America represented an estimated 28% of 2026 revenue. US cloud and enterprise networks retain substantial installed 100G QSFP28 populations alongside ongoing upgrades toward 400G, 800G and 1.6T.
Europe accounted for an estimated 20% of the market in 2026. Demand is linked to established telecom and enterprise networks, where interoperability, optical link budgets and replacement support influence purchasing decisions.
South America and the Middle East and Africa represent smaller markets. The report identifies Brazil and other regional markets as part of its country-level coverage, with demand shaped by network upgrades and optical equipment qualification.
Competitive Landscape and Key Companies
The 100G Optical Transceivers Market includes manufacturers and suppliers serving optical communication infrastructure, data-center connectivity and related passive or active network components.
Semiconductor Insight identifies the following companies in the competitive landscape: Finisar Corporation, Lumentum Holdings Inc. and Broadcom.
Competition is influenced by product performance, system compatibility, manufacturing capability, pricing, supply continuity and the ability to meet customer qualification requirements. The report also examines company positioning and relevant industry developments.
What Does the 100G Optical Transceivers Market Report Cover?
The Semiconductor Insight study examines market size, revenue, type and application segmentation, regional performance, competitive positioning and the commercial factors influencing 100G optical transceiver purchases. It also evaluates installed-base demand, replacement cycles and competitive pressure from higher-speed technologies.
The report covers SFF, SFP, QSFP, CFP, XFP and CXP types, along with Metropolitan Area, Remotely and Internal Data Center applications. Regional coverage includes North America, Europe, Asia-Pacific, South America and the Middle East and Africa.
The study also considers regional performance across North America, Europe, Asia-Pacific, South America, and the Middle East and Africa, with country-level coverage as specified in the report.
Key Questions Answered by the Study
The report helps industry participants evaluate questions including:
• What is the current 100G Optical Transceivers Market size?
• How large will the market become by 2036?
• What CAGR is stated in the report?
• Which type holds the largest market share?
• Which application represents the largest demand segment?
• Which region leads the 100G optical transceivers market?
• Why does 100G demand continue as higher-speed optics expand?
• What challenges affect the adoption of 100G modules?
• Which form factors are included in the report?
• Who are the key companies profiled?
• What is the role of QSFP28 in 100GbE networks?
• Which regions are included in the market analysis?
Explore the full 100G Optical Transceivers Market forecast and competitive analysis: https://semiconductorinsight.com/report/global-100g-optical-transceivers-market/
Get a Sample Report copy for free: https://semiconductorinsight.com/download-sample-report/
About Semiconductor Insight
Semiconductor Insight provides market intelligence and industry research covering semiconductor technologies, electronic components, communication systems, advanced manufacturing and related technology markets. Its research focuses on market sizing, forecasting, competitive landscapes, technology trends, segmentation and regional analysis to support strategic decision-making across the technology ecosystem.
Contact Semiconductor Insight
Website: https://www.semiconductorinsight.com


