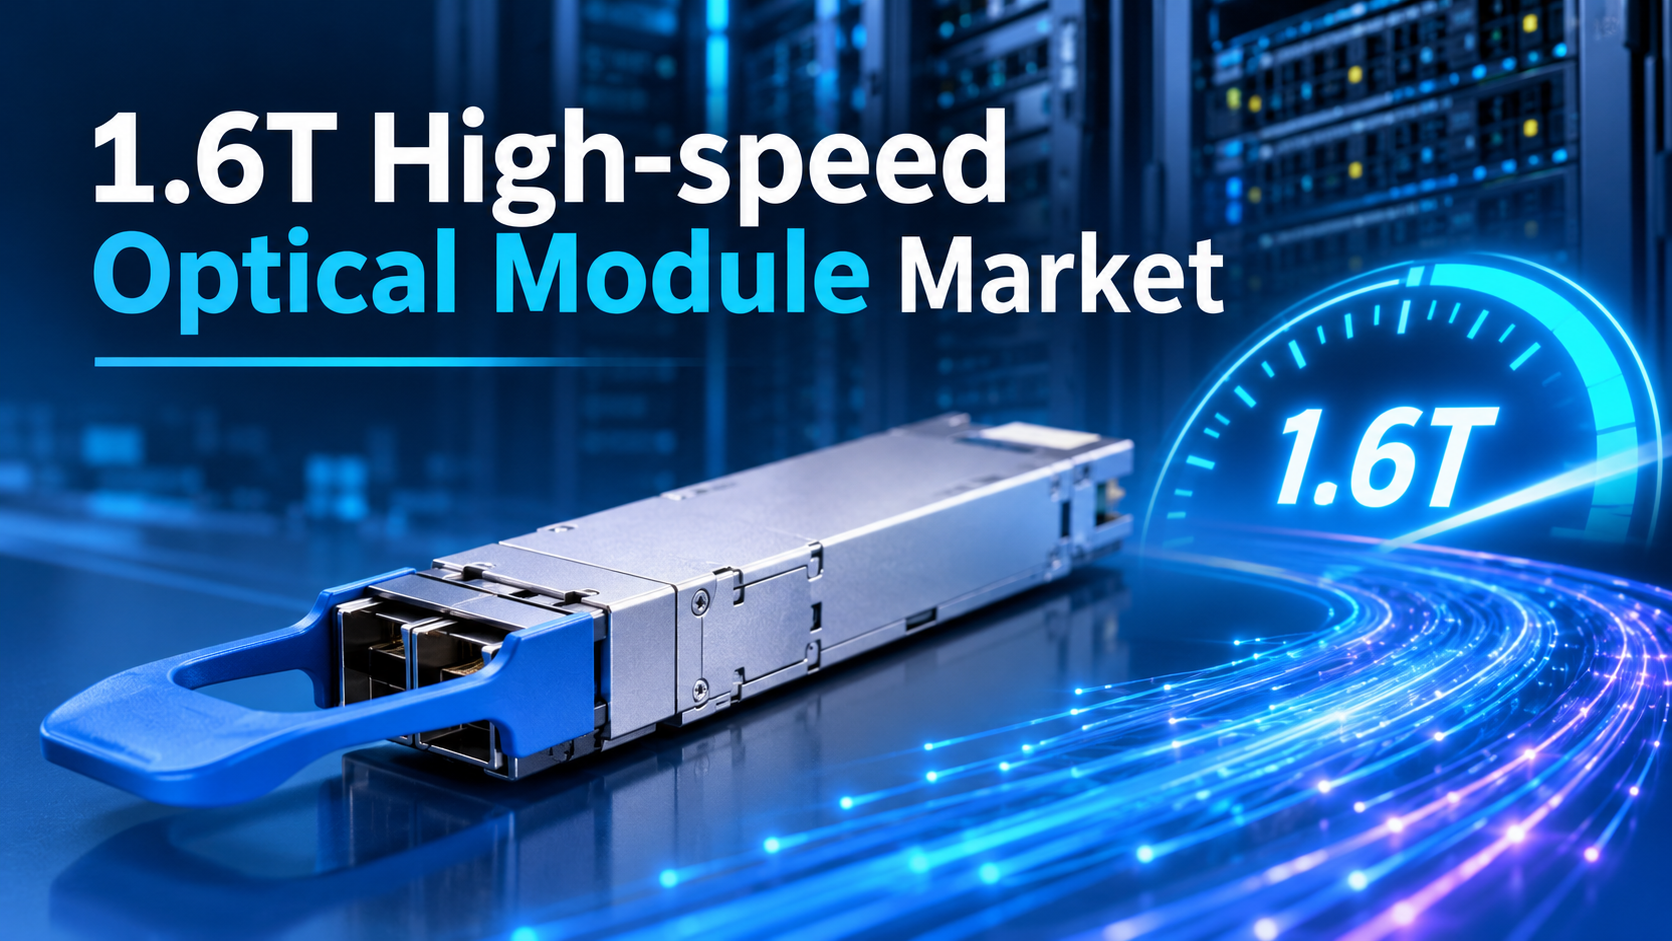
1.6T High-speed Optical Module Market to Reach USD 10,576 Million by 2032 as AI Data-Center Bandwidth Demand Accelerates

The rapid expansion of artificial intelligence workloads and hyperscale cloud infrastructure is increasing the need for optical interconnects capable of moving very large volumes of data with low latency. As networks transition beyond established 400G and 800G platforms, 1.6T high-speed optical modules are emerging as an important option for next-generation data-center connectivity.
According to SemiconductorInsight, the 1.6T High-speed Optical Module Market was valued at USD 1,793 million in 2025 and is expected to reach USD 10,576 million by 2032, reflecting a CAGR of 26.0% during the forecast period stated on the report page. The technology supports aggregate transmission rates of 1.6 Tbps and is used across hyperscale data centers, cloud-computing networks and AI-training clusters. The source reports approximately 654,300 units produced in 2025, average pricing of about USD 3,000 per unit, production capacity of around 810,000 units and average gross margins of 32%.
Explore the complete 1.6T High-speed Optical Module Market Market analysis
Why Is 1.6T High-speed Optical Connectivity Becoming Important for Data Centers?
Data-center networks are handling increasingly demanding workloads as generative AI, distributed cloud services and high-performance computing expand. These applications create substantial traffic between processors, storage systems and network switches, making bandwidth density and latency central considerations in infrastructure planning.
A 1.6T optical module provides an aggregate data rate of 1.6 Tbps, typically using multi-channel architectures and advanced modulation such as PAM4. The higher capacity can help operators increase throughput within constrained rack and network footprints while reducing the number of separate links required for a given traffic load.
The technology is also relevant to the migration from 400G and 800G links. As operators refresh network infrastructure, optical modules must meet tighter power, thermal and signal-integrity requirements while remaining compatible with the broader switching and cabling environment.
This combination of bandwidth, integration and power-efficiency considerations is positioning 1.6T modules as a developing component of AI-oriented data-center architecture.
AI Workloads Are Accelerating the Demand for Higher Bandwidth
One of the major factors influencing the 1.6T High-speed Optical Module Market is the rapid growth of AI model training. Large GPU clusters generate intensive east-west traffic, increasing the need for high-capacity links between compute nodes and network fabrics.
Semiconductor Insight identifies scaling bandwidth for cloud-native workloads as a key market driver. Operators are seeking compact, power-efficient transceivers that can sustain high per-lane data rates and aggregate bandwidth without creating excessive cabling complexity.
Silicon photonics integration is another important development. Integrating driver ASICs and photonic components more closely can reduce assembly steps, improve thermal performance and support more predictable system-level economics.
The migration to 1.6T is therefore not simply a speed upgrade. It is also connected to network consolidation, rack-density planning and the ability to support geographically distributed AI workloads.
Receive your Free Sample Report today: Download Sample Report
Silicon Photonics and Advanced Packaging Are Expanding the Technology Landscape
Silicon photonics is a central technology area within the 1.6T high-speed optical module ecosystem. The report identifies integration advances as a factor that can lower cost per gigabit while supporting compact, multi-channel module designs.
Advanced packaging is becoming increasingly important because optical chips, lasers, modulators, photodetectors, DSPs, driver ASICs and transimpedance amplifiers must operate together while preserving signal integrity at multi-terabit speeds.
The market includes several technology approaches, including Silicon Photonics, Electro-Absorption Modulated Laser (EML), Vertical Cavity Surface Emitting Laser (VCSEL) and Coherent Optical Light. These technologies address different integration, reach and performance requirements.
Emerging modulation techniques such as PAM4 can increase the amount of data carried per lane. The report also discusses supply-chain integration and packaging as important areas shaping product development.
AI Training Clusters and Hyperscale Data Centers Create Additional Demand
Data centers represent a core application for 1.6T high-speed optical modules because operators need to connect high-performance switches, servers and storage infrastructure at increasing bandwidth levels.
AI training clusters are a particularly important demand area. Large-scale GPU fabrics require high-density interconnects and low latency, while parallel optical architectures can support communication among large groups of processors.
Telecommunications backbone networks and high-performance computing centers are also included in the report's application segmentation. Their requirements vary according to transmission distance, network architecture and capacity planning.
These applications broaden the addressable market beyond conventional cloud data centers and create opportunities for suppliers able to qualify products for different link distances and system environments.
Power Efficiency and Network Integration Are Becoming Competitive Priorities
Power consumption per bit is an important consideration as data-center operators expand high-density computing infrastructure. Higher bandwidth in a compact module can help reduce the number of physical links and simplify cable management.
Co-packaging and closer integration of optical and electronic components are being explored to shorten electrical paths, improve signal integrity and manage latency at higher data rates.
The report also highlights the importance of manufacturing capabilities, testing infrastructure and engineering expertise. Multi-terabit products require careful validation to ensure reliable performance across operating conditions.
These developments indicate that suppliers compete not only on headline transmission speed but also on thermal design, integration capability, manufacturing yield and long-term reliability.
Manufacturing Yield and Supply-Chain Readiness Remain Important Market Drivers
Scaling production of 1.6T modules requires tight control over waveguide geometry, optical performance and assembly processes. Small manufacturing variations can affect eye-diagram quality and increase the number of units that fail qualification.
Supply-chain dependence is another consideration. The report identifies critical components such as high-quality InP lasers and low-loss polymer waveguides as inputs sourced from a relatively narrow supplier base.
Although higher bandwidth and improved energy efficiency can support favorable system economics, operators must evaluate the initial investment required for modules, switching platforms and associated infrastructure.
The market's commercial development will therefore depend on balancing performance improvements with manufacturing yield, component availability and the cost of upgrading existing networks.
Access the Full Report for In-Depth Insights: 1.6T High-speed Optical Module Market
Manufacturing Yield and Infrastructure Compatibility Remain Key Challenges
Despite the strong bandwidth proposition, producing 1.6T modules consistently presents technical challenges. Tight process windows and demanding signal-integrity requirements can increase manufacturing complexity and place pressure on unit costs.
Capital expenditure sensitivity can also delay adoption. Data-center operators may postpone multi-terabit upgrades when existing 100G, 400G or 800G equipment remains serviceable or when budgets do not support a full network refresh.
Compatibility with legacy infrastructure is another restraint. Existing routers, switches and backplanes may require firmware changes, recabling or broader equipment upgrades before 1.6T modules can be deployed.
The report further identifies supply-chain concentration, extended testing and validation cycles, and the shortage of qualified engineering resources as factors that can affect deployment schedules.
Where Are the Biggest Opportunities Emerging?
Edge-computing deployments represent one potential opportunity as 5G fronthaul, autonomous-vehicle telemetry and mixed-reality applications increase demand for high-capacity connections outside traditional core data centers.
Sustainability initiatives may also support adoption. Higher data throughput per watt can help operators improve energy efficiency and align network investments with environmental objectives.
Another opportunity is the development of high-density port strategies for metro and edge networks. Network architects are evaluating ways to increase aggregate bandwidth without proportionally expanding rack footprints.
Suppliers with expertise in silicon photonics, advanced packaging and high-speed testing may be positioned to address these emerging requirements.
1.6T High-speed Optical Module Market Segmentation
The report evaluates the market across key product and application categories, providing a structured view of demand and deployment requirements.
By type, the market is divided into:
• Silicon Photonics
• Electro-Absorption Modulated Laser (EML)
• Vertical Cavity Surface Emitting Laser (VCSEL)
• Coherent Optical Light
By application, the market covers:
• Data Centers
• Telecommunications Backbone Networks
• AI Training Clusters
• High-Performance Computing (HPC) Centers
• Others
This segmentation is relevant for manufacturers and buyers because technical requirements vary by transmission performance, deployment environment, network architecture and end-user application.
View the complete 1.6T High-speed Optical Module Market segmentation and forecast: Market segmentation and forecast
Regional 1.6T High-speed Optical Module Market Outlook
Asia-Pacific is a major market for 1.6T high-speed optical modules, supported by data-center expansion and network modernization in China, South Korea and Japan. Investment in high-capacity fiber backbones and hyperscale cloud infrastructure is supporting demand for terabit-level connectivity.
North America benefits from hyperscale cloud operators, AI infrastructure investment and the presence of major technology companies. Demand is linked to the upgrade of data-center fabrics and the deployment of high-performance computing clusters.
Europe's market is influenced by cloud infrastructure, telecommunications modernization and the need for efficient interconnects. Suppliers must address performance, power and system-integration requirements across varied network environments.
Other regions are developing through cloud, telecom and edge-computing investment. The report's regional analysis covers the broader market landscape, although it does not provide a 2026–2034 regional revenue series in the cited summary.
Competitive Landscape and Key Companies
The 1.6T High-speed Optical Module Market includes manufacturers and suppliers serving optical communication infrastructure, data-center connectivity and related passive or active network components.
Semiconductor Insight identifies the following companies in the competitive landscape: Nokia Corporation, Samsung Electronics, Sont Technologies, Cisco Systems, Optech Technology, Eoptolink Technology, Accelink Technologies, Broadcom Inc., Marvell Technology, InnoLight Technology, Solis Optoelectronics, Lumentum Holdings, Universal Scientific Industrial (USI), Jabil and AOI.
Competition is influenced by product performance, system compatibility, manufacturing capability, pricing, supply continuity and the ability to meet customer qualification requirements. The report also examines company positioning and relevant industry developments.
What Does the 1.6T High-speed Optical Module Market Report Cover?
The Semiconductor Insight study examines market size, production, revenue, pricing, gross margins, competitive positioning, technology trends and industry dynamics. It also evaluates market drivers, challenges, restraints, opportunities and the factors influencing adoption of high-speed optical modules.
The report provides segmentation by technology, application, end user, packaging form and transmission distance. It also examines regional market conditions, key companies, supply-chain considerations and the competitive environment across the 1.6T high-speed optical module ecosystem.
The study also considers regional performance across North America, Europe, Asia-Pacific, South America, and the Middle East and Africa, with country-level coverage as specified in the report.
Key Questions Answered by the Study
The report helps industry participants evaluate questions including:
• What is the current 1.6T High-speed Optical Module Market size?
• How large is the market expected to become by 2032?
• What is the CAGR stated in the report?
• How are AI training workloads influencing demand?
• What role does silicon photonics play in module development?
• Which technologies are covered in the market segmentation?
• Which applications are driving adoption of 1.6T modules?
• What challenges affect manufacturing yield and product qualification?
• How does compatibility with legacy infrastructure affect adoption?
• Which regions are important to the market?
• Who are the leading companies covered in the report?
• What opportunities are emerging in edge computing and sustainable data centers?
Explore the full 1.6T High-speed Optical Module Market forecast and competitive analysis: Full market report
Get a Sample Report copy for free: Download Sample Report
About Semiconductor Insight
Semiconductor Insight provides market intelligence and industry research covering semiconductor technologies, electronic components, communication systems, advanced manufacturing and related technology markets. Its research focuses on market sizing, forecasting, competitive landscapes, technology trends, segmentation and regional analysis to support strategic decision-making across the technology ecosystem.
Contact Semiconductor Insight
Website: www.semiconductorinsight.com


