China’s Heat Pump Expansion Is Connecting Clean Heating With Industrial Efficiency
China’s heat pump sector is developing alongside the country’s broader transition toward electrified heating, energy efficiency, and lower-carbon thermal systems. Demand is being shaped by residential heating and cooling needs, clean-heating initiatives, industrial decarbonization, and technological improvements. At the same time, relatively high upfront costs and installation requirements remain important considerations for wider adoption.
According to the China heat pump market analysis published by MarkNtel Advisor, the sector was valued at around USD 13.31 billion in 2025 and is projected to reach USD 22.59 billion by 2032, expanding at a CAGR of 9.6% during 2026–2032. Air-source heat pumps represented approximately 85% of the sector in 2025, while residential applications accounted for around 72%.
Clean Heating Policies Are Supporting Adoption
Government policy is an important factor influencing heat pump deployment in China. The country’s carbon-peaking and carbon-neutrality objectives are encouraging greater electrification of heating and reducing dependence on coal-based thermal systems.
The International Energy Agency notes that China was the world’s largest heat pump market for buildings in 2023 and accounted for more than one-quarter of global sales. Heat pump adoption has been supported by clean-heating policies, particularly in regions seeking to reduce coal use while maintaining reliable space heating.
China also issued the GB 19577-2024 national energy-efficiency standard, covering minimum allowable energy-efficiency values and energy grades for heat pumps and water chillers. The standard came into effect in February 2025, reinforcing the importance of equipment efficiency in the sector.
Air-Source Systems Maintain a Strong Position
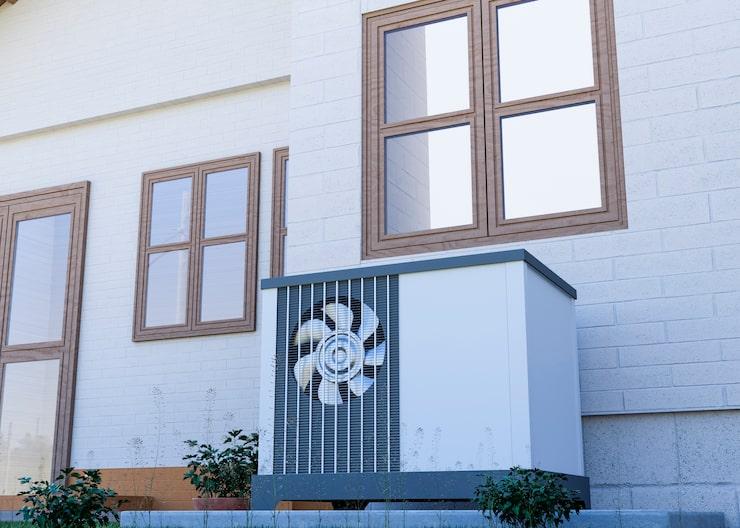
Air-source heat pumps accounted for approximately 85% of China’s sector in 2025. Their leading position reflects relatively straightforward installation, lower infrastructure requirements, and flexibility across residential and commercial applications.
Unlike ground-source systems, air-source equipment does not require extensive ground-loop infrastructure. This can reduce installation complexity and make the technology more adaptable to different building environments.
Technological improvements are also expanding operating capabilities. Improvements in compressors, low-temperature performance, controls, and refrigerant technologies are helping manufacturers develop systems that can operate across a broader range of climatic conditions.
Air-to-air and air-to-water configurations can support different applications, including space heating, cooling, and domestic hot-water production. Their versatility contributes to the continued importance of air-source systems within China's heat-pump landscape.
Residential Applications Remain the Core Demand Base
Residential users accounted for approximately 72% of China's heat pump sector in 2025. Household demand is supported by the need for space heating, cooling, and domestic hot water, particularly in areas where clean-heating programs are encouraging alternatives to coal-based systems.
Heat pumps can also provide multiple services through a single technology. Reversible systems can support both heating and cooling, while air-to-water configurations can provide space heating and hot water.
The IEA reports that heat pumps already accounted for 8% of heating-equipment sales for buildings in China in 2022 and have become common in some central and southern areas, where the same systems can provide heating and cooling.
This multifunctional capability can become particularly relevant in regions where seasonal requirements vary significantly.
Industrial Applications Are Broadening the Opportunity
Heat pump deployment is increasingly moving beyond residential buildings into industrial applications. China's industrial sector consumes substantial amounts of heat, and low- and medium-temperature processes can be technically suitable for heat pump applications.
The IEA estimates that nearly 20% of industrial heat consumption in China is below 200°C, a range where heat pump technologies can potentially contribute to electrification.
This creates opportunities in industries requiring process heat for applications such as drying, washing, food processing, and other low- or medium-temperature operations. Higher-temperature heat pump development could further broaden the technology's industrial relevance.
Recent developments reflect this direction. The market analysis identifies high-temperature heat pump technologies as an emerging area of innovation, with manufacturers working to extend operating temperatures and improve performance for industrial users.
Technology Development Is Improving Efficiency
Technological innovation is becoming a central feature of China's heat pump industry. Manufacturers are developing systems with improved compressors, advanced controls, lower-carbon refrigerants, and enhanced low-temperature performance.
Artificial intelligence is also beginning to influence residential equipment. AI-enabled systems can adjust operation according to usage patterns and environmental conditions, potentially improving energy management while maintaining indoor comfort.
The market analysis also highlights growing investment in testing and research infrastructure for R290-based heat pump systems. Such developments indicate that refrigerant selection and system efficiency are becoming closely connected areas of product innovation.
China's manufacturing ecosystem provides an additional advantage. The IEA's 2026 Heat Pump Monitor notes that China leads in heat pump sales and cost-competitive manufacturing, supported by integrated domestic supply chains.
Upfront Costs Remain a Barrier
Despite the sector's growth, heat pumps can require substantial initial investment. Equipment, installation, system design, and commissioning can make the upfront cost higher than conventional heating alternatives.
The market analysis identifies installation complexity and a shortage of sufficiently trained installers as important constraints. Proper system sizing and commissioning are particularly important because heat pump performance depends on equipment selection, building characteristics, climate conditions, and operating settings.
These factors can be more challenging for industrial and larger residential systems. Expanding installer training, improving technical standards, and developing financing mechanisms could therefore influence adoption alongside equipment innovation.
Regional Adoption Is Concentrated in Key Provinces
Eastern and northern provinces, including Shandong, Jiangsu, Guangdong, and the Beijing-Tianjin-Hebei region, represent important areas for heat pump deployment. Population density, urban development, industrial activity, and heating requirements contribute to their significance.
Industrial clusters in provinces such as Shandong and Jiangsu can support process-heating applications, while urban residential development provides a large base for building-related systems. Local incentives and clean-heating initiatives can further influence adoption.
These regional differences highlight the importance of matching heat pump technologies with local climate, building types, industrial requirements, and energy infrastructure.
China’s Heat Pump Transition Is Becoming Broader
China's heat pump industry is increasingly moving beyond conventional residential heating toward a broader role in electrification and energy efficiency. Air-source systems remain dominant because of their flexibility and relatively straightforward installation, while residential applications continue to provide the largest demand base.
At the same time, industrial heat, high-temperature technologies, smart controls, and lower-carbon refrigerants are expanding the range of potential applications. Policy support and energy-efficiency standards are reinforcing this transition, although upfront costs and installation capabilities remain important constraints.
The sector's longer-term direction is therefore closely connected with China's wider energy transformation. Heat pumps are becoming part of an evolving thermal infrastructure in which residential comfort, industrial efficiency, electrification, and emissions reduction increasingly intersect.
 Portuguese
 English
 Arabic
 French
 Spanish
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek