Industrial Gas Infrastructure: Cryogenic Equipment Market Size and Regional Dynamics
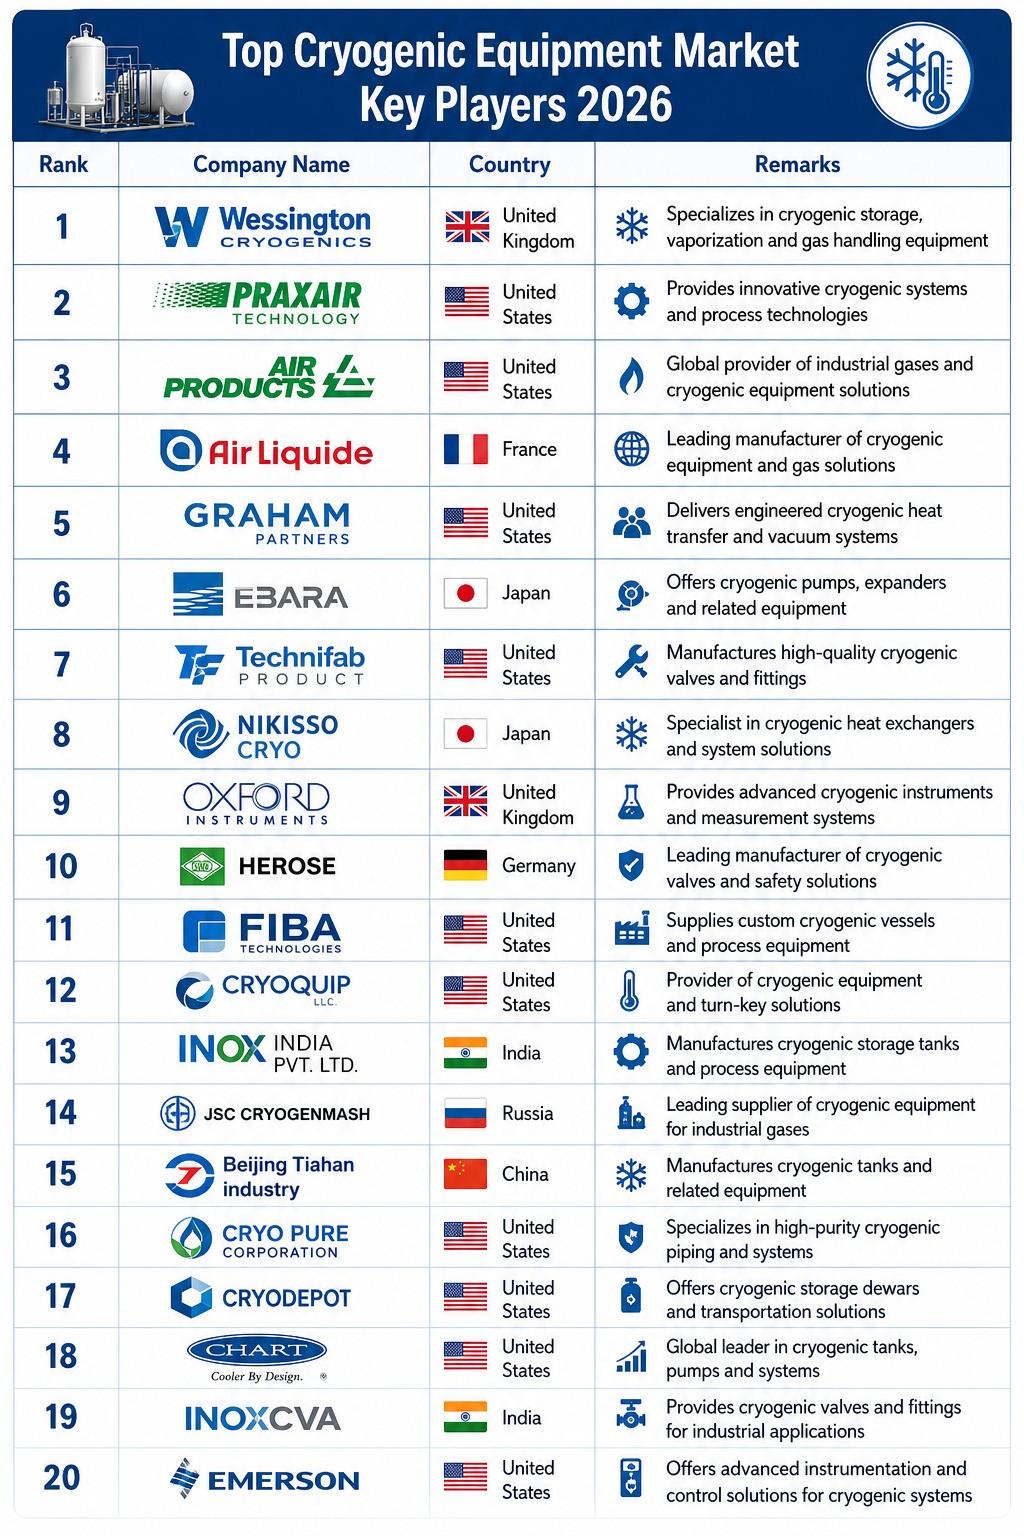
Global Cryogenic Equipment Market Set for Sustained Expansion as LNG Infrastructure, Clean Energy Transition, and Industrial Gas Demand Drive Market Value Toward USD 43.91 Billion by 2034
The global energy transition, coupled with the relentless modernization of chemical manufacturing, semiconductor fabrication, and life sciences cold chains, is triggering a profound structural transformation across the global cryogenic equipment market. Operating in extreme temperature domains beneath minus 150 degrees Celsius, cryogenic systems have evolved from specialized industrial niches into core infrastructure components of contemporary global commerce. Today, the world relies on sophisticated cryogenic containment vessels, vacuum-insulated transfer pipelines, specialized control valves, vaporizers, and cryogenic pumps to liquify, preserve, transport, and regasify gases that fuel modern civilization.
As geopolitical realignments push sovereign nations toward domestic energy security, the demand for flexible maritime and overland distribution of liquefied natural gas (LNG) has reached record heights. Concurrently, the global push toward a decarbonized economy is accelerating investments in liquid hydrogen transport corridors, specialized ammonia networks, and carbon capture and storage (CCS) hubs. This structural energy evolution, alongside soaring requirements for ultra-pure atmospheric gases in metallurgy and cleanroom semiconductor manufacturing, is unlocking capital deployment across advanced thermodynamic equipment manufacturing.
The convergence of metallurgical innovation, vacuum thermal insulation engineering, and Internet of Things (IoT)-enabled real-time telemetry is turning cryogenic engineering into a strategic technological frontier. Today’s industrial leaders and energy operators can no longer afford equipment failures, boil-off gas losses, or logistical downtime. Consequently, decision-makers are reallocating capital budgets toward resilient, high-integrity cryogenic storage systems, dynamic regasification setups, and automated handling equipment designed to withstand extreme thermal gradients and cryogenic pressures over multi-decade lifecycles.
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/25719/
Executive Overview and Market Valuation Trajectory
Comprehensive market assessments published by Maximize Market Research indicate that the global cryogenic equipment market stood at USD 25.36 Billion in 2025. Driven by ongoing construction of large-scale LNG export and import terminals, aggressive expansion across chemical production hubs, and the emergence of green hydrogen pilot networks, overall industry revenue is projected to expand at a compound annual growth rate (CAGR) of 6.29% from 2026 through 2034. This sustained capital expenditure will propel the global market valuation to nearly USD 43.91 Billion by the close of 2034.
This sustained upward trajectory demonstrates the resilience of high-value industrial hardware across shifting macroeconomic cycles. The handling of liquefied atmospheric and hydrocarbon gases requires specialized, capital-intensive engineering that adheres to strict international safety and quality standards, creating high barriers to entry. As emerging economies scale their domestic steel output, expand clean healthcare operations, and build gas-fired baseload electricity networks, cryogenic equipment manufacturers are realizing durable, long-term order books backed by continuous aftermarket service, maintenance, and fleet replacement contracts.
Transformative Catalysts Driving Global Cryogenic Equipment Growth
The commercial momentum across the global cryogenic equipment sector is sustained by several interlinked technological, regulatory, and macroeconomic forces:
-
Strategic Buildout of Global Liquefied Natural Gas (LNG) Infrastructure: Natural gas serves as a crucial bridge fuel in the global transition away from emissions-heavy coal. However, moving gas across vast oceans requires chilling methane to minus 162 degrees Celsius, shrinking its volume by 600 times into a liquid state. The expansion of floating storage and regasification units (FSRUs), large-scale liquefaction plants, maritime LNG bunkering vessels, and overland cryogenic ISO tank containers represents a massive hardware deployment cycle that demands specialized tanks, vaporizers, and insulated cryogenic pumps.
-
Clean Hydrogen and Decarbonization Ecosystems: National zero-emission initiatives and industrial decarbonization strategies place substantial emphasis on clean hydrogen. Transporting bulk hydrogen efficiently over long distances requires cryogenic liquefaction at a challenging minus 253 degrees Celsius. Developing materials, double-walled vacuum vessels, and high-pressure cryogenic transfer systems capable of safely containing liquid hydrogen without hydrogen embrittlement or severe boil-off losses is accelerating commercial research and high-margin product launches.
-
High-Purity Industrial Gases for Semiconductor and Electronics Fabrication: The worldwide construction of mega-scale semiconductor fabrication facilities requires immense, continuous supplies of ultra-high-purity (UHP) cryogenic nitrogen, argon, and oxygen. Liquid nitrogen is used in vast volumes for purging, thermal cooling, and maintaining inert cleanroom atmospheres. Chipmakers are partnering directly with industrial gas producers to build on-site cryogenic air separation units (ASUs) and vacuum-jacketed distribution loops directly connected to cleanroom tools.
-
Biomedical, Pharmaceutical, and Cellular Therapy Cold Chains: The rapid evolution of regenerative medicine, messenger RNA vaccines, monoclonal antibodies, and biological sample preservation has altered life-science storage requirements. Conventional refrigeration is inadequate for long-term cell preservation; biological materials require temperatures below minus 130 degrees Celsius to halt metabolic activity. Specialized automated cryogenic freezers, liquid nitrogen dewars, and dry vapor shippers are now standard equipment across clinical laboratories, biopharma manufacturing plants, and cord blood repositories worldwide.
-
Advanced Space Exploration and Satellite Launch Services: The commercial space industry is experiencing a new era marked by reusable launch vehicles and expanding satellite constellations. Modern rocket engines rely heavily on cryogenic liquid oxygen (LOX), liquid hydrogen (LH2), and liquid methane as propellants. Launch sites and commercial aerospace facilities are investing heavily in stationary cryogenic propellant storage farms, rapid-chill transfer systems, and high-flow cryogenic valves to support rigorous launch cadences.
Comprehensive Market Segmentation Analysis
By Product Type: Tanks Form the Structural Foundation While Valves and Pumps Drive Functional Control
The global cryogenic equipment market is segmented by product into Tanks, Valves, Vaporizers, Pumps, Vacuum-Insulated Piping, and Other Auxiliary Systems.
Cryogenic Tanks account for the dominant market revenue share. These vessels serve as the physical containment standard for liquefied gases, ranging from small mobile liquid cylinders and ISO intermodal containers to massive flat-bottom field-erected storage tanks holding hundreds of thousands of cubic meters at coastal import terminals. Modern cryogenic tanks utilize double-walled construction featuring carbon steel outer jackets, stainless steel or nickel-alloy inner vessels, and an evacuated annular space packed with perlite insulation or multilayer vacuum superinsulation (MLI). With global industrial safety mandates prioritizing boil-off gas minimization, advanced tank manufacturing focuses on eliminating thermal bridges and maximizing structural integrity under extreme thermal contraction.
Concurrently, Cryogenic Valves and Pumps represent the highest-margin and fastest-growing equipment segments. Cryogenic valves—encompassing globe, gate, ball, butterfly, and safety relief valves—must maintain hermetic sealing at sub-zero temperatures where conventional elastomeric seals turn brittle and fail. Manufacturers employ extended-bonnet architectures with specialized PCTFE or PTFE packings to insulate the stem seal from the cryogenic stream. Similarly, submerged cryogenic motor pumps and centrifugal transfer pumps are critical components for transferring high-density liquids across LNG terminals, fuel dispensers, and chemical plants, requiring high-precision hydrodynamic design to prevent cavitation.
Vaporizers and Heat Exchangers play an equally critical operational role in transforming cryogenic liquids back into usable ambient-temperature gases. Ambient air vaporizers, water-bath vaporizers, and shell-and-tube configurations are deployed at municipal peak-shaving facilities, industrial gas distribution hubs, and hospital oxygen systems to handle continuous phase transitions reliably.
By Cryogenic Gas: Nitrogen and Oxygen Lead Volume, Hydrogen Emerges as the Growth Frontier
The market is categorized by gas type into Nitrogen, Oxygen, Natural Gas (LNG), Argon, Hydrogen, Helium, and Other Specialty Gases.
Nitrogen and Oxygen continue to represent the largest volume distribution. Liquid nitrogen is an indispensable cooling medium and inerting agent across food freezing, metal fabrication, chemical purging, and life sciences. Liquid oxygen is fundamental to basic oxygen steelmaking, wastewater processing, aerospace propulsion, and clinical respiratory medical gas networks. The sheer geographic scale of global air separation infrastructure ensures steady, recurring replacement and expansion cycles for liquid oxygen and nitrogen hardware.
Liquefied Natural Gas (LNG) is the fastest-growing revenue contributor among hydrocarbons, driven by expanding international maritime transport and gas-fired electrical grids. Concurrently, Liquid Hydrogen and Helium represent technically demanding, high-value specialty frontiers. Liquid helium, operating near absolute zero at minus 269 degrees Celsius, is essential for cooling superconducting magnets in hospital Magnetic Resonance Imaging (MRI) scanners and particle accelerators. Its scarcity demands closed-loop cryogenic recovery and zero-loss reliquefaction systems.
By Application and End-User: Energy and Metallurgy Power Global Deployment
By application, the sector is divided into Storage, Distribution, and Processing. By end-user, the market serves Energy & Power, Chemicals & Petrochemicals, Metallurgy, Healthcare & Pharmaceuticals, Food & Beverage, and Aerospace.
The Energy & Power sector represents the largest consumer of cryogenic hardware, driven by LNG value chains, clean hydrogen investments, and gas turbine fuel supplies. The Metallurgy and Chemical industries follow closely, utilizing atmospheric gases within blast furnaces, metal cutting, oxidation reactions, and plastics manufacturing. Healthcare continues to gain rapid market share as regional hospital systems decentralize oxygen supply security by installing larger on-site cryogenic liquid oxygen storage bulk tanks instead of relying on high-pressure cylinder deliveries.
Regional Perspectives and Geopolitical Landscape
Asia-Pacific: The Dominant Engine of Global Cryogenic Demand
The Asia-Pacific region held the largest market share in 2025 and is projected to maintain its leadership through 2034. Driven by rapid industrialization, extensive urban infrastructure development, and massive manufacturing footprints across China, India, Japan, South Korea, and Southeast Asia, the region is the world's primary consumer of industrial gases and imported LNG.
China's national pipeline network expansion, coal-to-gas industrial conversions, and aggressive investments in domestic semiconductor manufacturing are driving unprecedented demand for cryogenic ASUs, bulk storage tanks, and vacuum-jacketed distribution lines. India is experiencing parallel growth as the country expands its city gas distribution (CGD) networks, scales domestic steelmaking capacity, and modernizes its healthcare supply chains. Backed by strong local equipment manufacturing clusters and massive state-directed infrastructure budgets, Asia-Pacific remains the primary growth driver of the global industry.
North America: Resource Extraction and Clean Energy Innovation
North America represents an established, high-value market centered around hydrocarbon production, energy exports, and advanced aerospace and life sciences applications. Driven by vast shale gas production across the United States, the region has transformed into one of the world's leading exporters of LNG. This status has triggered heavy capital investment in Gulf Coast export terminals, liquefaction trains, and cryogenic marine bunkering systems.
Furthermore, substantial federal incentives for clean hydrogen production, carbon sequestration, and commercial space ventures are generating demand for high-performance cryogenic storage solutions, advanced transfer valves, and mobile liquid transport trailers. Private equity and venture investments across North American biopharma manufacturing further support steady procurement of high-tier biomedical cryopreservation systems.
Europe: Decarbonization Policies and Energy Supply Realignment
Europe is characterized by an urgent need to diversify natural gas import routes away from legacy pipeline dependencies, leading to rapid installations of floating and land-based LNG import terminals across Germany, the Netherlands, France, and the United Kingdom. European operators place immense emphasis on thermal efficiency, low-emission operations, and minimized boil-off gas rates.
Simultaneously, the European Union's aggressive regulatory mandates for renewable hydrogen and carbon capture are encouraging engineering consortia to pioneer commercial-scale liquid hydrogen bunkering systems and cryogenic carbon dioxide transport vessels. The region's stringent European Pressure Equipment Directive (PED) and ATEX safety standards position Europe as a benchmark for safety engineering and premium equipment design.
Middle East, Africa, and Latin America: Expanding Production and Export Terminals
In the Middle East, colossal LNG production expansion programs—particularly in Qatar, the United Arab Emirates, and Saudi Arabia—are generating substantial demand for high-capacity cryogenic processing modules, mega-scale storage tanks, and distribution networks. Latin America, led by Brazil and Argentina, is focusing on exploiting regional natural gas fields and modernizing mining and chemical processing operations, providing steady regional demand for industrial gas storage and transport equipment.
Strategic Industry Challenges: Thermal Stress, Capital Costs, and Supply Chain Risk
Despite favorable market dynamics, manufacturers and project developers must navigate distinct technical, financial, and regulatory challenges:
-
Extreme Thermodynamic Stresses and Material Embrittlement: Standard structural steels undergo ductile-to-brittle transitions at sub-zero temperatures, making them vulnerable to catastrophic cracking. Fabricating cryogenic equipment requires specialized metallurgy, including austenitic stainless steels, 9% nickel alloys, aluminum alloys, and brass. Welding and fabricating these alloys requires certified processes to ensure joint integrity across decades of repeated thermal expansion and contraction cycles.
-
Capital Intensity and Prolonged Project Delivery Timelines: Building large-scale cryogenic facilities—such as atmospheric air separation units or coastal LNG regasification terminals—requires hundreds of millions of dollars in upfront capital. Extended engineering, procurement, and construction (EPC) cycles expose equipment suppliers and project sponsors to inflation, interest-rate fluctuations, and supply chain disruptions for specialized components like vacuum insulation panels and forged valves.
-
Boil-Off Gas (BOG) Management and Economic Losses: Cryogenic liquids absorb ambient thermal energy over time, causing continuous vaporization known as boil-off gas. If unmitigated, BOG increases vessel pressure, requiring either venting (wasting valuable product and emitting greenhouse gases) or energy-intensive on-site re-liquefaction. Designing cost-effective insulation materials that minimize heat ingress during transport remains a continuous engineering battle.
-
Strict Safety Mandates and Regulatory Complexity: The combination of high pressures, cryogenic liquid expansion ratios (where liquid oxygen expands over 800-fold into gas), and flammable or asphyxiating properties demands adherence to stringent codes (such as ASME Section VIII, EN 13445, and CGA standards). Compliance costs, specialized safety testing, and lengthy certification cycles can slow product entry into new regional markets.
Future Business Role and Strategic Decision Framework
To capture long-term market share, maintain pricing margins, and adapt to the shifting industrial gas landscape, equipment manufacturers and engineering leaders should implement five strategic initiatives:
-
Develop Future-Proofed Multi-Gas Capabilities: Manufacturers should design flexible cryogenic equipment capable of handling multiple fluids with minimal retrofitting. Storage tanks, valving systems, and transport trailers that can be adapted from LNG to liquid hydrogen, ammonia, or liquid carbon dioxide provide energy operators with long-term asset security as green fuels mature.
-
Integrate IoT Telemetry and Predictive Boil-Off Analytics: Equipment suppliers must move beyond selling passive containment hardware. Embedding wireless sensors, vacuum integrity monitors, automated pressure relief logging, and acoustic leak detectors transforms static vessels into smart assets. Offering predictive analytics software that alerts facility operators to vacuum decay or imminent seal degradation before failure occurs opens valuable recurring service revenue streams.
-
Pioneer Advanced Superinsulation and Aerogel Technologies: Capital allocators should invest in proprietary, non-flammable insulation formulations. Moving beyond conventional perlite to next-generation vacuum insulation panels (VIPs), aerogel blankets, and automated vacuum maintenance systems significantly reduces boil-off rates, helping clients meet corporate sustainability and efficiency goals.
-
Localize Component Sourcing and Fabrication Footprints: The global concentration of specialty cryogenic component manufacturing has repeatedly caused supply bottlenecks during peak construction periods. Establishing localized manufacturing, assembly, and testing facilities within high-growth regions like India, Southeast Asia, and the Gulf States mitigates geopolitical shipping disruptions and reduces transport logistics costs for oversized vessels.
-
Forge Strategic Partnerships with EPC Contractors and Industrial Gas Majors: Because the purchase of cryogenic hardware is typically integrated into massive infrastructure buildouts, equipment manufacturers should establish long-term framework agreements with tier-one engineering, procurement, and construction (EPC) conglomerates and industrial gas operators (such as Linde, Air Liquide, and Air Products). Securing preferred-vendor status for modular process skids and standardized valve packages ensures stable production scheduling across multi-year delivery cycles.
A Clear Vision for the Future of Cryogenic Infrastructure
The future of the global cryogenic equipment market is fundamentally intertwined with the sustainable industrialization of our world. As nations move away from carbon-heavy fuels without sacrificing industrial output, the capacity to liquify, store, and transport molecules at ultra-low temperatures represents an indispensable engineering foundation. Over the coming decade, we will see the widespread commercialization of automated cryogenic fuel bunkering for deep-sea shipping, the establishment of decentralized liquid hydrogen supply networks for heavy-duty freight, and the integration of closed-loop cryocoolers within quantum computing data centers.
Cryogenic equipment is transitioning from an invisible industrial utility into an active driver of global energy security and decarbonization. Manufacturers and corporate decision-makers who invest in metallurgical integrity, digital performance tracking, and standardized modular manufacturing will not only secure resilient commercial leadership—they will build the physical pathways that carry the world toward a cleaner, more prosperous future.
About Maximize Market Research
Maximize Market Research publishes sector forecasts, competitive analysis, and consulting insight for teams evaluating demand, competition, pricing, and growth strategy across high-value industries. By fusing quantitative market intelligence with extensive qualitative stakeholder interviews across global supply chains, Maximize Market Research equips corporate decision-makers, private equity leaders, and strategic planners with authoritative market clarity to navigate disruptive industry trends.
Contact Information
MAXIMIZE MARKET RESEARCH PVT. LTD.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
Phone: +91 9607365656
Email: sales@maximizemarketresearch.com
 Russian
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Romaian
 Portuguese (Brazil)
 Greek