United States Silver Nanowire Transparent Conductive Film Market to Reach USD 200 Million by 2034 at 10.8% CAGR
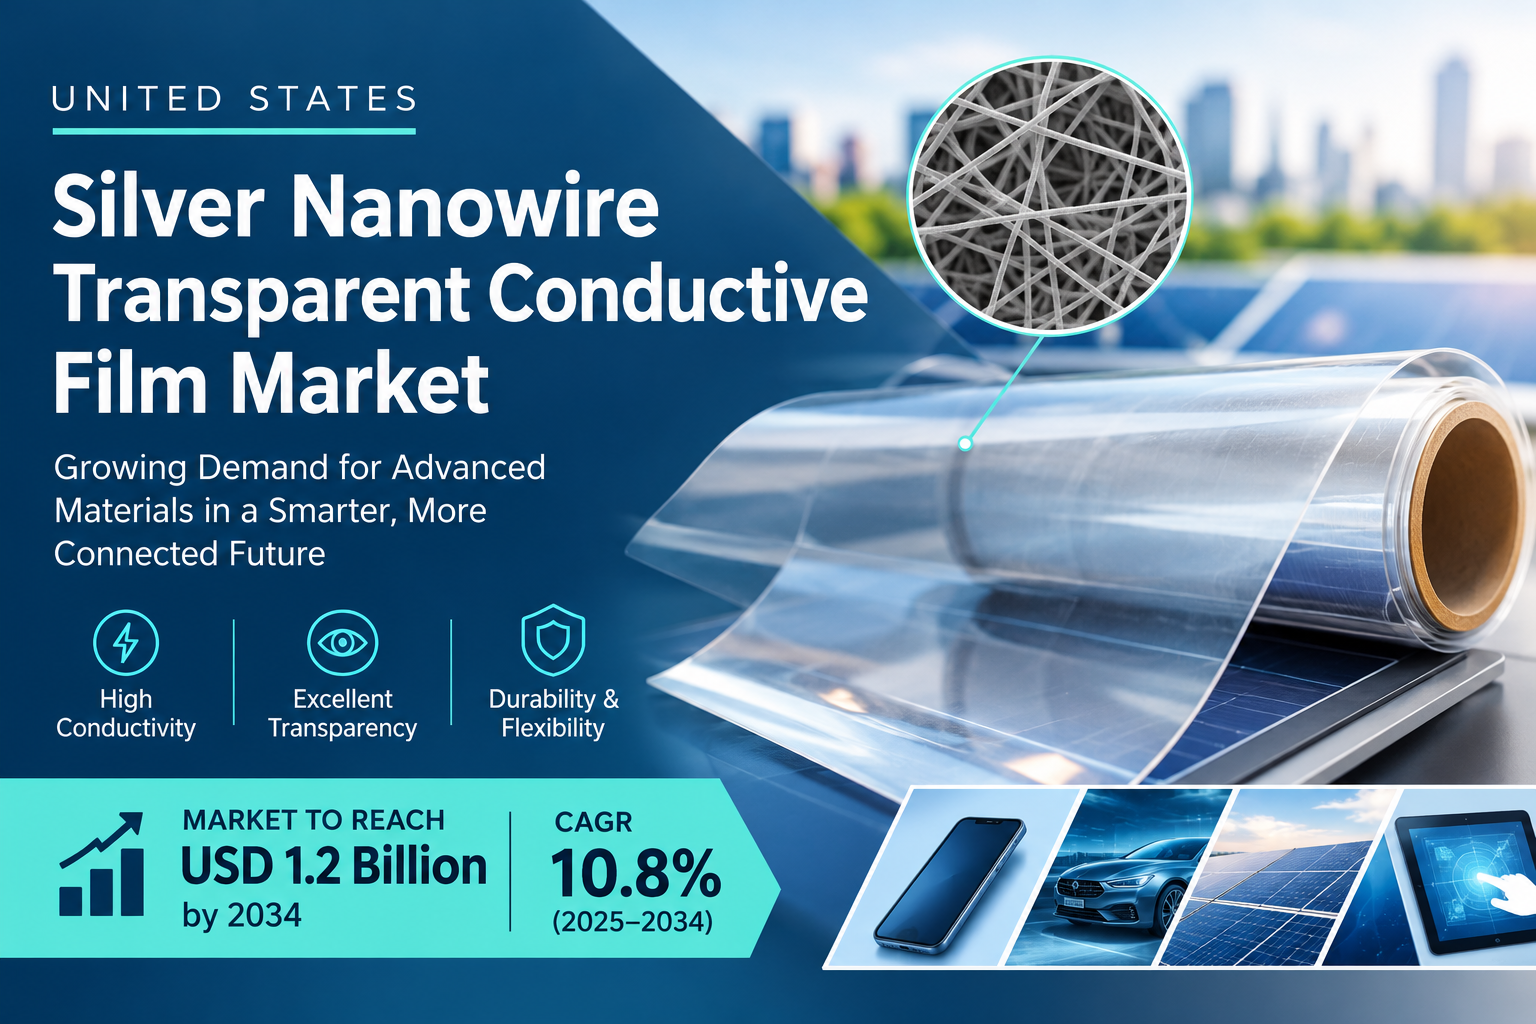
According to 24ChemicalResearch’s market research, the United States Silver Nanowire Transparent Conductive Film Market was valued at USD 86 million in 2025. It is projected to grow from approximately USD 94 million in 2026 to USD 200 million by 2034, exhibiting a compound annual growth rate (CAGR) of 10.8% during the forecast period. Demand is supported by the use of flexible, optically clear conductive films in advanced displays, consumer electronics, automotive interfaces, photovoltaic cells, and smart-window applications.
View the complete report: https://www.24chemicalresearch.com/reports/279927/united-states-silver-nanowire-transparent-conductive-film-market
Silver nanowire transparent conductive film consists of a network of silver nanowires integrated onto a flexible, optically clear substrate. Its combination of electrical conductivity, optical transparency, light weight, flexibility, and corrosion resistance makes it relevant to next-generation touch panels, foldable OLED displays, photovoltaic cells, and smart windows.
What Is Driving the United States Silver Nanowire Transparent Conductive Film Market?
Market growth is being supported by rising adoption in high-end display technologies, expanding automotive applications, and opportunities in smart windows and building-integrated photovoltaics. At the same time, high raw-material costs, complex production processes, and demanding certification requirements remain important market challenges.
Rising Adoption in High-End Display Technologies
Silver nanowire films are being adopted for premium smartphones, tablets, flexible OLED displays, and foldable devices because they combine optical clarity with electrical performance. The report notes that the U.S. premium smartphone and tablet cohort has expanded by nearly 4% annually over the past five years, with cumulative market value surpassing USD 3.2 billion. Nanowire arrays can maintain haze below 2% while enabling conductive pathways at thicknesses below 200 nm. These characteristics are encouraging display supply chains to adapt to high-purity silver materials and advanced deposition processes.
Integration into Automotive HMI and Electroluminescent Panels
Automotive applications are another demand driver. The U.S. segment recorded a 6.8% year-on-year increase in infotainment and connectivity modules, which increasingly require flexible conductive coatings. Silver nanowire films can reduce panel weight and signal loss while supporting slimmer head-up displays, instrument clusters, and other vehicle interfaces. The report also describes pilot-program adoption in which more than 95% of power-train control units across major U.S. technology hubs adopted silver nanowire films over the past two years, replacing indium-tin oxide.
Opportunities in Smart Windows and Building-Integrated Photovoltaics
Energy-efficient building design is creating potential applications for transparent conductive films in smart glass, adjustable-tinting systems, interactive façades, and building-integrated photovoltaics. The films’ conductivity, flexibility, and low sheet resistance support their use in lightweight glass and façade systems. The report also identifies opportunities to integrate sensor arrays into conductive layers for connected devices and Internet of Things applications.
Technology Development and Manufacturing Scale-Up
Advances in high-aspect-ratio silver nanowires, nanowire synthesis, encapsulation, and roll-to-roll processing are helping manufacturers pursue improved optical and electrical performance at scale. The report notes that research and development investments have increased by roughly 30% since 2022. Roll-to-roll processing is identified as a leading manufacturing approach because of its scalability and suitability for large-area films.
Market Challenges and Restraints
Production requires high-purity silver, clean processing environments, specialized deposition equipment, and post-treatment or encapsulation to help maintain performance. These requirements can increase capital needs, production time, and cost per square meter. Certification related to flammability, electromagnetic interference, and long-term UV exposure can also delay commercialization. In addition, humidity, temperature cycling, chemical exposure, and repeated flexing may affect long-term film performance.
Market Segmentation Insights
The report examines the market across nanowire diameter, application, end user, performance requirement, and manufacturing process.
By Type (Nanowire Diameter)
· Diameter below 15 nm
· Diameter 15 nm–30 nm
· Diameter above 30 nm
The 15 nm–30 nm diameter segment is described as the mainstream category because it balances optical transparency and electrical conductivity for display and touch-panel applications. Smaller diameters serve niche applications requiring ultra-thin profiles, while larger diameters can support applications requiring greater mechanical robustness.
By Application
· LED screens and touch panels
· Solar battery
· Automotive glass and architectural glass
· Other applications
LED screens and touch panels are identified as the dominant application segment. Demand is supported by larger, responsive, bendable displays, curved and foldable devices, bezel-free designs, and the integration of touch functionality across display surfaces.
Additional Segmentation
The report also segments the market by end user—consumer electronics OEMs, automotive manufacturers, solar panel producers, and smart building integrators. Consumer electronics OEMs are described as the leading end-user group. Performance categories include ultra-flexible and foldable films, high-durability and stability films, and standard-performance films; ultra-flexible and foldable films are identified as a dynamic segment. Manufacturing processes include solution-coating techniques, roll-to-roll processing, and vacuum-deposition methods, with roll-to-roll processing highlighted for its scalability.
Regional Market Analysis
North America is identified as the leading region, while Asia-Pacific is an emerging region. Within the United States, the report highlights several distinct regional demand patterns:
West Coast: California and Washington
California and Washington are described as a leading technology cluster due to advanced manufacturing capabilities, intellectual-property portfolios, and proximity to display and semiconductor vendors. Research universities, local government, and industry collaborations support research and development, nanowire ink development, deposition methods, and commercialization of flexible OLED and automotive display variants.
Midwest: Automotive and Industrial Applications
The Midwest’s infrastructure and industrial development are supporting potential demand in electric-vehicle powertrain components, dashboards, ambient lighting, temperature-sensing panels, transparent heaters, and HVAC controls. Smart-grid installations, logistics hubs, and battery-pack manufacturing also contribute to the region’s application landscape.
Texas–Oklahoma Corridor: Renewable Energy and Monitoring
Texas and Oklahoma are highlighted for the use of transparent conductive films in solar farms, concentrated-solar power plants, and nanowire-based sensors for leak detection and pipeline monitoring. The region’s semiconductor supply chain, research activity, and energy-sector infrastructure are described as supporting technology transfer and pilot deployments.
Northeast: Medical and Aerospace Applications
In the Northeast, research universities and defense contractors are exploring flexible transparent electrodes for medical diagnostics, wearable monitoring, and aerospace instrumentation. Collaboration among academic institutions, laboratories, and companies supports prototyping and development of materials designed to meet application-specific performance and safety requirements.
Competitive Landscape and Key Players
The report identifies 3M Company and DuPont de Nemours, Inc. as major participants, alongside specialized companies including ClearJet, Indium Corporation, Ag-Technology Inc., and Applied Nanotech Corp. The market’s competitive focus includes nanowire formulation, high-aspect-ratio architectures, roll-to-roll deposition, vacuum-deposition processes, oxidation protection, encapsulation, and application-specific customization.
The report describes established suppliers as investing in manufacturing capabilities and working with consumer-electronics OEMs, semiconductor fabs, and display-panel manufacturers. Specialized suppliers focus on nanowire inks, chemically stabilized slurries, composite nanowires, and scalable coating processes for automotive heaters, transparent photovoltaics, flexible sensors, and wearable applications.
Report Summary
The United States Silver Nanowire Transparent Conductive Film Market is projected to expand as demand grows for flexible, transparent conductive materials in advanced displays, consumer electronics, automotive interfaces, solar applications, and smart buildings. Market development is supported by advances in nanowire fabrication and scalable manufacturing, while high silver costs, production complexity, supply-chain vulnerability, and certification requirements remain constraints.
Key Report Highlights
· The market was valued at USD 86 million in 2025 and is projected to reach USD 200 million by 2034.
· The market is projected to grow from approximately USD 94 million in 2026, at a CAGR of 10.8% during the forecast period.
· North America is identified as the leading region, with Asia-Pacific described as an emerging region.
· High-end displays, flexible OLED and foldable devices, automotive infotainment and interfaces, photovoltaic cells, and smart windows are important demand areas.
· Nanowire diameter categories are below 15 nm, 15 nm–30 nm, and above 30 nm; the 15 nm–30 nm segment is described as mainstream.
· LED screens and touch panels are identified as the dominant application segment.
· Consumer electronics OEMs are the leading end-user group, while ultra-flexible and foldable films are a dynamic performance segment.
· Roll-to-roll processing is highlighted as a leading manufacturing approach for scalable large-area film production.
· Key companies profiled include 3M Company, DuPont de Nemours, Inc., ClearJet, Indium Corporation, Ag-Technology Inc., and Applied Nanotech Corp.
· Key constraints include high-purity silver costs, specialized production equipment, complex processing, supply-chain risks, and regulatory testing requirements.
Frequently Asked Questions: United States Silver Nanowire Transparent Conductive Film Market
Q: What is the market size and forecast for the United States Silver Nanowire Transparent Conductive Film Market?
A: The market was valued at USD 86 million in 2025 and is projected to reach USD 200 million by 2034. The report also gives an approximate 2026 value of USD 94 million and a CAGR of 10.8%.
Q: What are the key growth drivers?
A: Key drivers include demand for high-end and foldable displays, adoption in automotive infotainment and connectivity modules, and opportunities in smart windows, photovoltaic cells, and building-integrated photovoltaics.
Q: Which region leads the market?
A: North America is identified as the leading region. Within the United States, the report highlights California and Washington, the Midwest, the Texas–Oklahoma corridor, and the Northeast for different technology and application clusters.
Q: Which type segment is the mainstream category?
A: The 15 nm–30 nm nanowire diameter segment is described as the mainstream category because it balances optical transparency and electrical conductivity.
Q: Which application segment is dominant?
A: LED screens and touch panels are identified as the dominant application segment.
Q: Who are the key companies profiled?
A: The report identifies 3M Company, DuPont de Nemours, Inc., ClearJet, Indium Corporation, Ag-Technology Inc., and Applied Nanotech Corp.
Q: What challenges could affect market growth?
A: Challenges include high-purity silver costs, specialized deposition equipment, complex processing and encapsulation, supply-chain vulnerability, performance under extreme environmental conditions, and certification requirements.
View the Complete Report
Download the free sample report
Contact Us
Website: Chemical Market Research | Global Chemical Market Research Reports | 24ChemicalResearch
Asia: +91 9169162030
 Greek
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)