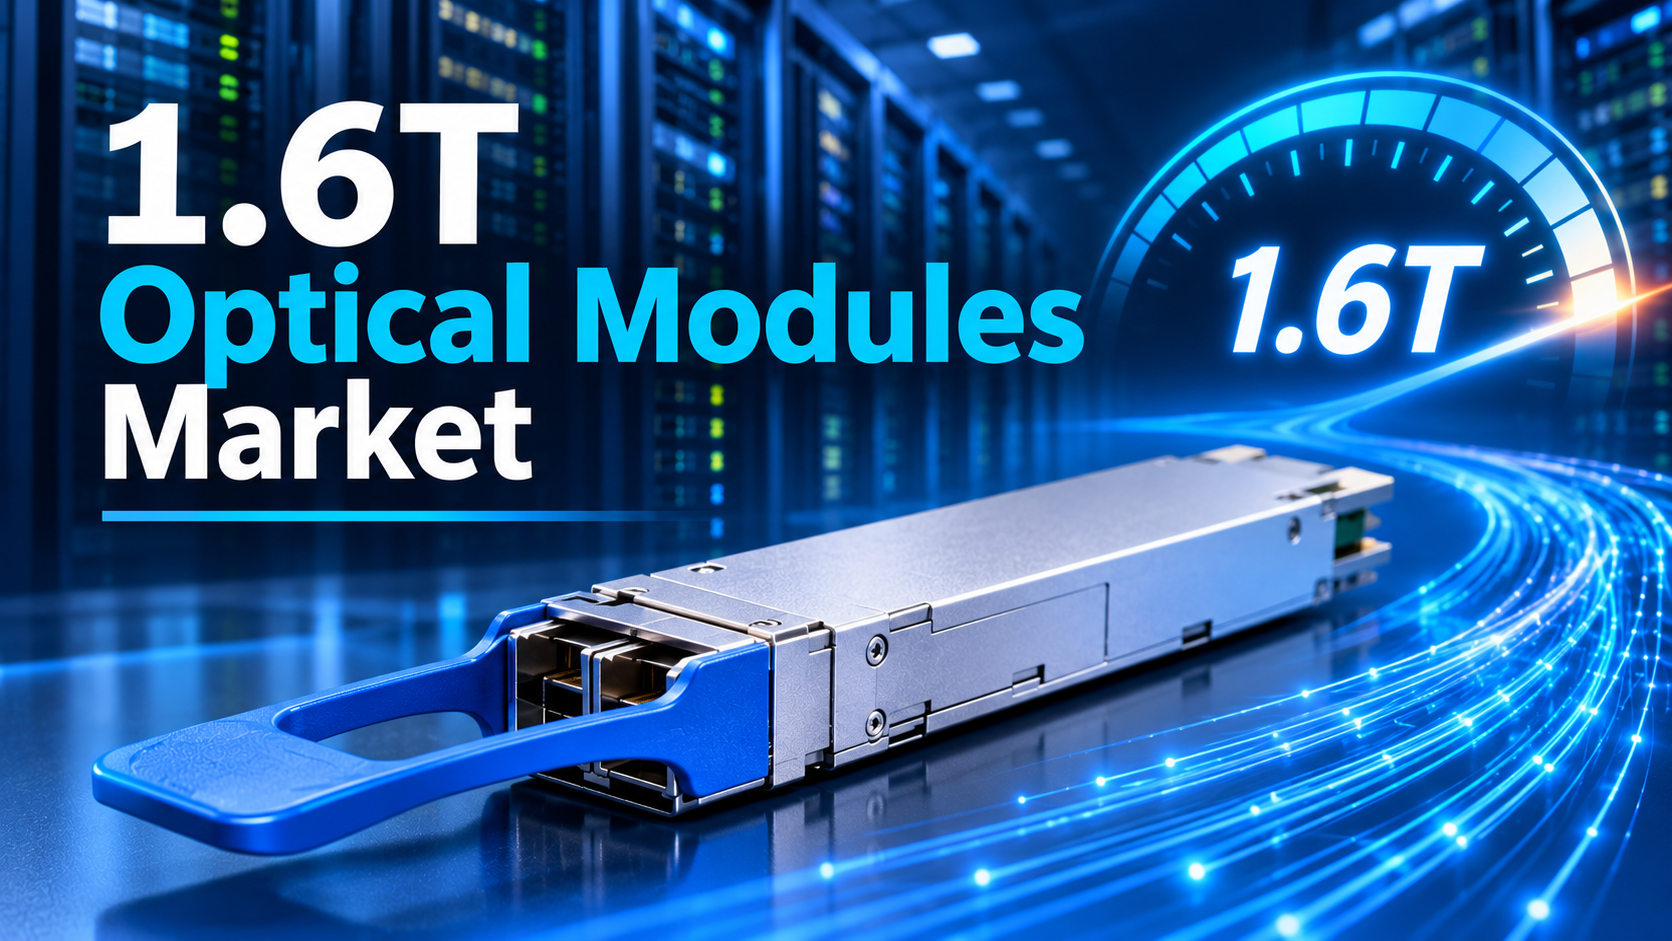
1.6T Optical Modules Market to Reach USD 10,576 Million by 2032 as AI-Centric Data Centers Upgrade Network Capacity

The rapid expansion of generative artificial intelligence, cloud computing and hyperscale data centers is reshaping the requirements of optical networking infrastructure. As data-center operators seek greater bandwidth density and lower power consumption, 1.6T optical modules are gaining importance as a next-generation connectivity solution.
According to SemiconductorInsight, the 1.6T Optical Modules Market was valued at USD 2,133 million in 2025 and is expected to reach USD 10,576 million by 2032, reflecting a CAGR of 26.0% during the forecast period stated on the report page. These modules deliver 1,600 Gbps aggregate bandwidth, commonly through eight 200 Gbit/s lanes, and use OSFP or OSFP-XD packaging with high-speed DSPs and silicon-photonic or EML components. The report links growth to AI model training, higher bandwidth density per rack and advances in silicon photonics.
Explore the complete https://semiconductorinsight.com/report/1-6t-optical-modules-market/
Why Are 1.6T Optical Modules Becoming Important for Hyperscale Data Centers?
Data-center operators are facing rising network traffic from AI-enabled workloads, real-time analytics and cloud-native applications. These workloads require high-capacity connections among servers, switches and GPU clusters, increasing pressure on established optical interconnect technologies.
1.6T optical modules are designed to provide aggregate bandwidth of 1,600 Gbps, typically through an eight-lane architecture carrying 200 Gbit/s per lane. They support high-speed data transfer across short-, medium- and longer-distance links, depending on the optical configuration.
The technology is commonly associated with OSFP and OSFP-XD packaging and integrates DSP chips with silicon-photonic or EML lasers and photodetectors. These components are intended to support the performance and density requirements of next-generation data-center networks.
As AI infrastructure expands, 1.6T modules are becoming part of the broader transition from 400G and 800G connectivity toward higher-bandwidth network architectures.
AI Workloads Are Accelerating the Demand for Higher-Speed Optical Modules
One of the major factors influencing the 1.6T Optical Modules Market is the increase in bandwidth requirements across hyperscale data centers. AI model training and real-time analytics generate intensive traffic that places pressure on existing network links.
Semiconductor Insight identifies rising bandwidth requirements in hyperscale data centers as a key market driver. Operators are adopting higher-density optical connections to increase throughput while managing power consumption and rack space.
Co-packaging optics with application-specific integrated circuits is another important development. Bringing optical functions closer to ASICs can shorten electrical paths, reduce latency and improve signal integrity at 1.6T speeds.
These changes are encouraging optical-module suppliers and network-equipment companies to align product roadmaps with the deployment cycles of AI-focused data centers.
Receive your Free Sample Report today: https://semiconductorinsight.com/download-sample-report/
Silicon Photonics and Co-Packaged Optics Are Expanding the Technology Landscape
Silicon photonics is emerging as a preferred technology because it can integrate optical functions with established silicon manufacturing processes. The report highlights its potential to support cost-effective scaling, high-density routing and improved power efficiency.
Co-packaged optics is another important trend. Integrating transceiver functions directly with ASIC platforms can reduce electrical path length and support signal integrity as data rates increase.
The market includes Silicon Photonics, Externally Modulated Laser (EML), VCSEL and Coherent Optical Light. Each approach addresses different performance, distance, integration and cost requirements.
Advanced wafer-level packaging and high-speed DSP integration are also influencing the supply chain. Manufacturers are working to fit more functionality into OSFP and OSFP-XD form factors while controlling thermal and manufacturing constraints.
AI Training Clusters and Cloud Service Providers Create Additional Demand
AI training clusters are among the most dynamic application areas for 1.6T optical modules. Large GPU fabrics require high-density interconnects and low-latency communication to keep model-training workloads operating efficiently.
Data centers remain a central application because operators are upgrading network fabrics to support greater bandwidth per rack. The modules can support connections among switches, servers and compute clusters.
Supercomputing centers and telecommunications backbone networks are also included in the report's application segmentation. Their requirements vary according to network reach, architecture and traffic profile.
Cloud service providers and AI compute companies are important end users because they control substantial data-center infrastructure and prioritize scalable, high-performance optical connectivity.
Packaging Density and Power Efficiency Are Becoming Competitive Priorities
Power efficiency is an important consideration as data centers deploy more powerful compute systems. Higher bandwidth density can reduce the number of physical links required and help manage power consumption per transmitted bit.
OSFP and OSFP-XD packaging are central to the current module landscape. The report notes the importance of thermal management, lane architecture and compatibility with existing high-speed optical ecosystems.
Suppliers are also investing in DSP integration, tunable lasers and advanced packaging to improve performance and manufacturing scalability. These developments can influence cost, reliability and time-to-market.
The market's development will depend on how effectively manufacturers combine optical design, electronic integration and packaging capabilities to meet hyperscale deployment requirements.
Higher Network Capacity Is Creating New Commercial Opportunities
The migration toward 1.6T links creates opportunities for suppliers serving hyperscale data centers, AI compute firms and high-performance networks. Higher aggregate bandwidth can help operators expand capacity without proportionally increasing physical rack infrastructure.
Co-packaged optics and silicon photonics may improve system economics by reducing electrical path length and supporting more integrated architectures. These developments are relevant to operators evaluating long-term network operating costs.
At the same time, 1.6T modules currently carry higher bill-of-materials costs than mature 400G platforms. Limited silicon-photonic wafer capacity and custom driver IC requirements can affect pricing and adoption decisions.
Cost competitiveness will therefore remain an important factor as the industry moves from early deployments toward broader production and qualification.
Access the Full Report for In-Depth Insights: https://semiconductorinsight.com/report/1-6t-optical-modules-market/
Cost Parity and Supply-Chain Complexity Remain Key Challenges
Despite their performance advantages, 1.6T optical modules face cost challenges compared with established 400G solutions. Higher component costs and specialized manufacturing requirements can make price-sensitive operators cautious about replacing existing equipment.
Supply-chain complexity is another restraint. Production may involve silicon-photonic wafers, driver ASICs and package assembly across different geographies, creating exposure to logistics bottlenecks and raw-material shortages.
Legacy infrastructure compatibility can also slow adoption. Some carrier networks use chassis and backplane designs that cannot accommodate the electrical and thermal profiles of 1.6T modules without substantial engineering work.
The report also notes that evolving interface standards and regional regulatory certifications can increase qualification effort and delay deployment.
Where Are the Biggest Opportunities Emerging?
High-density port strategies represent one potential opportunity as network architects design chassis capable of supporting multiple 1.6T ports on a single line card. This can increase aggregate bandwidth without requiring a proportional expansion of rack space.
Software-defined networking platforms may also create opportunities by supporting programmable control of ultra-high-speed optical interfaces. This can help service providers allocate bandwidth for low-latency applications.
Green data-center initiatives provide another opportunity because improved power per bit can support energy-efficiency targets. Operators are increasingly evaluating network components in the context of overall facility power and cooling requirements.
Suppliers with early co-packaged optics designs, OSFP-XD manufacturing capabilities and strong silicon-photonic platforms may be positioned to participate in the next upgrade cycle.
1.6T Optical Modules Market Segmentation
The report evaluates the market across key product and application categories, providing a structured view of demand and deployment requirements.
By type, the market is divided into:
• Silicon Photonics
• EML (Externally Modulated Laser)
• VCSEL
• Coherent Optical Light
By application, the market covers:
• Data Centers
• AI Training Clusters
• Supercomputing Centers
• Telecommunications Backbone Networks
• Others
This segmentation is relevant for manufacturers and buyers because technical requirements vary by transmission performance, deployment environment, network architecture and end-user application.
View the complete 1.6T Optical Modules Market segmentation and forecast: https://semiconductorinsight.com/report/1-6t-optical-modules-market/
Regional 1.6T Optical Modules Market Outlook
Asia-Pacific is a major center of 1.6T optical module activity, supported by hyperscale data-center rollouts and telecommunications modernization in China, Japan and South Korea. The region's cloud infrastructure investment is creating demand for high-capacity optical interconnects.
North America benefits from large cloud-service providers and AI compute investment. The report highlights the role of hyperscale infrastructure and network upgrades in supporting adoption of 1.6T modules.
Europe's market is influenced by telecommunications backbone requirements, data-center development and the need for efficient optical networking. Suppliers must address interoperability, packaging and performance requirements.
Other regional markets are developing as cloud and telecom operators expand network capacity. The report's regional analysis considers the broader global market, although the cited page does not provide a separate 2026–2034 regional forecast series.
Competitive Landscape and Key Companies
The 1.6T Optical Modules Market includes manufacturers and suppliers serving optical communication infrastructure, data-center connectivity and related passive or active network components.
Semiconductor Insight identifies the following companies in the competitive landscape: InnoLight Technology, Eoptolink Technology, Accelink Technologies, Solis Optoelectronics, Nokia Corporation, Sont Technologies, Cisco Systems, Lumentum Holdings, Broadcom Inc., Marvell Technology, OpenLight Photonics, Sumitomo Electric Industries, Samsung Electronics, Foxconn Interconnect Technology, Celestica, Coherent Corp and Universal Scientific Industrial (USI).
Competition is influenced by product performance, system compatibility, manufacturing capability, pricing, supply continuity and the ability to meet customer qualification requirements. The report also examines company positioning and relevant industry developments.
What Does the 1.6T Optical Modules Market Report Cover?
The Semiconductor Insight study examines market size, revenue, production, competitive positioning, technology trends, supply-chain conditions and the factors influencing the adoption of 1.6T optical modules. It also evaluates market drivers, restraints, challenges and opportunities.
The report provides segmentation by type, application, end user, packaging form and transmission distance. It also examines regional market conditions and profiles key companies involved in optical-module design, manufacturing, integration and supply.
The study also considers regional performance across North America, Europe, Asia-Pacific, South America, and the Middle East and Africa, with country-level coverage as specified in the report.
Key Questions Answered by the Study
The report helps industry participants evaluate questions including:
• What is the current 1.6T Optical Modules Market size?
• How large will the market become by 2032?
• What CAGR is stated in the report?
• Why are AI data centers adopting 1.6T optical modules?
• What role does silicon photonics play in this market?
• Which technology types are covered in the report?
• Which applications are driving market demand?
• What packaging formats are used for 1.6T optical modules?
• What challenges could slow adoption?
• Which regions are important to the market?
• Who are the leading companies covered in the report?
• What opportunities are emerging from co-packaged optics?
Explore the full 1.6T Optical Modules Market forecast and competitive analysis: https://semiconductorinsight.com/report/1-6t-optical-modules-market/
Get a Sample Report copy for free: https://semiconductorinsight.com/download-sample-report/
About Semiconductor Insight
Semiconductor Insight provides market intelligence and industry research covering semiconductor technologies, electronic components, communication systems, advanced manufacturing and related technology markets. Its research focuses on market sizing, forecasting, competitive landscapes, technology trends, segmentation and regional analysis to support strategic decision-making across the technology ecosystem.
Contact Semiconductor Insight
Website: https://www.semiconductorinsight.com


